Iran–Kenya Trade: Opportunities, Barriers & Market Access
Iran and Kenya are seeking closer commercial ties, with pharmaceuticals, agriculture, industrial products and infrastructure among the proposed areas of cooperation. Existing trade data, however, points to a narrower and more revealing picture: a market already buying Iranian bitumen, a valuable tea trade facing unresolved obstacles, and several promising sectors where commercial access still needs to be established.
On October 14, 2026, the presidents of the Iranian and Kenyan chambers of commerce met in Nairobi to discuss expanding trade and investment between their countries.
The agenda covered a wide range of industries. Iranian businesses expressed interest in supplying pharmaceuticals, medical equipment, fertilizers and petrochemical products, while also participating in agricultural technology, infrastructure and industrial development projects.
Kenya was presented as a potential entry point into East Africa, supported by the Port of Mombasa and its connections to neighbouring markets. Iran, in turn, was described as a possible route for Kenyan businesses seeking access to Central Asia and Eurasia.
The meeting came during Nairobi’s Africa Commerce & Industry Summit, held on October 14–16, and followed a series of bilateral initiatives during 2025.
There is a commercial basis for closer cooperation, but the opportunity is more specific than the diplomatic language suggests.
Kenya already imports certain Iranian industrial products. Iran has historically been an important buyer of Kenyan tea. Some proposed sectors have established, although limited, trade flows. Others remain largely at the stage of discussions and prospective partnerships.
The useful question is therefore not how much the two countries could theoretically trade. It is which products and services can compete in the Kenyan market, reach buyers reliably and generate payments under existing conditions.
What the Trade Figures Actually Show
In 2024, Kenya reported imports worth approximately $18.3 million from Iran and exports worth $50.8 million to Iran, according to UN Comtrade data.
The composition of these flows is more informative than the total.
Kenya’s imports from Iran were concentrated in petroleum-related products, with smaller amounts of food preparations, fertilizers, pharmaceuticals and ceramics.
Exports in the opposite direction were dominated by tea and other products classified under the broader coffee, tea and spices category.
The relationship is therefore not a balanced exchange of diversified industrial goods. It largely connects selected Iranian manufactured or processed commodities with Kenyan agricultural exports.
There is also evidence of growth on the Iranian export side. Kenya’s reported imports from Iran rose to approximately $32.1 million in 2025, with petroleum-related products accounting for about $27.4 million.
These figures establish that some Iranian goods have already found Kenyan buyers. They do not, by themselves, demonstrate a broad market opening.
Trade statistics also require care when assessing a relationship affected by restrictions and disputes. Recorded exports, customs clearance, product origin and the practical ability to execute new contracts are related but separate questions.
Kenyan officials have continued to report problems affecting tea exports to Iran, even as historical trade statistics record substantial shipments.
For companies considering the market, the strongest starting point is consequently product-level evidence rather than ambitious targets for total bilateral trade.
Bitumen: An Established Market With Measurable Competition
Bitumen provides the clearest example of an existing Iranian export position in Kenya.
World Bank WITS data show that Kenya imported approximately $20.1 million of petroleum bitumen under HS 271320 in 2024.
Iran supplied around $5.9 million, equivalent to approximately 12,562 tonnes. It was Kenya’s second-largest reported supplier after the United Arab Emirates, which supplied about $7.5 million.
Oman, Kuwait, China and Turkey were also among the suppliers.
The important point is that Iranian bitumen is not an untested product in this market. Kenyan buyers have already purchased it in meaningful quantities.
The commercial question is whether Iranian exporters can maintain or expand that position against competing sources.
Price is one factor, but buyers of road-construction materials also need consistent product specifications, dependable delivery and suitable commercial terms.
Bitumen grades must match the requirements of the intended project. Packaging or bulk-handling arrangements must fit local storage and transportation infrastructure. Contractors and distributors must be able to receive material when construction schedules require it.
Importers also need to account for port handling, inland transportation, financing and any quality-testing obligations.
An apparently cheaper export quotation can lose its advantage once these costs are included.
This is particularly relevant when maritime transport or insurance becomes more expensive. Kenya’s location on the Indian Ocean creates a geographical connection with Iranian Gulf ports, but that proximity does not guarantee a reliable or economical shipment.
For exporters, a stronger market-entry strategy would begin with identifying established Kenyan bitumen distributors, road contractors and industrial buyers, then comparing the delivered cost of Iranian grades with products sourced from the UAE, Oman and other existing suppliers.
The opportunity is real because the trade already exists. Its expansion depends on execution rather than market awareness.
Pharmaceuticals: Demand Exists, but Regulation Determines Access
Healthcare was one of the principal sectors discussed in Nairobi.
Iran has substantial pharmaceutical manufacturing capabilities, and its private sector has expressed interest in both direct exports and joint production in Kenya.
The existing trade figures, however, indicate a relatively small commercial position.
Kenya reported approximately $558,000 in pharmaceutical imports from Iran in 2024, falling to about $233,000 in 2025.
This does not establish that Iranian medicines lack a market. It shows that existing shipments remain limited and that entry into the sector should not be treated as straightforward.
Kenya’s Pharmacy and Poisons Board regulates the registration, marketing authorization, importation and distribution of medicines and medical devices.
A product manufactured and approved in Iran cannot automatically be sold in Kenya. Manufacturers and importers must meet the applicable regulatory requirements, including product authorization, quality standards and licensing arrangements.
For medicines, market access may involve technical dossiers, registration costs, qualified local partners and an ongoing responsibility to maintain regulatory compliance.
These requirements change the economics of entering the market.
For a manufacturer selling a small range of low-value products, regulatory and distribution costs may absorb much of the potential margin. A company with a differentiated product, competitive manufacturing costs or an established Kenyan distribution partner may have a stronger position.
Joint production is another possibility, but it requires a different assessment.
A local facility needs sufficient demand, dependable input supplies, qualified personnel, regulatory approval and enough scale to justify its fixed costs.
For many firms, a distribution agreement or technical partnership may provide a more reasonable first step than immediately investing in manufacturing capacity.
The broader opportunity should therefore be evaluated product by product, with registration feasibility and buyer demand established before committing capital.
Agriculture: Fertilizers Are Only Part of the Opportunity
Agriculture offers several possible forms of cooperation, but they should not be grouped into a single market.
Kenya’s agricultural sector creates demand for fertilizers, irrigation systems, equipment, food-processing technologies and storage infrastructure. Iranian companies have capabilities in several of these areas.
There is also some evidence of existing trade. Kenya imported around $1.3 million of fertilizer products from Iran in 2024.
That provides a starting point for investigating further sales, although fertilizer demand depends on more than national agricultural output.
Different crops and soil conditions require different nutrient formulations. Procurement is influenced by seasonal demand, government policies, distribution networks and the availability of competing supplies.
International fertilizer prices and shipping conditions can also substantially affect purchasing decisions.
The 2026 disruptions in Gulf shipping have added another source of uncertainty to global fertilizer supply chains. For Iranian exporters, however, higher international prices do not necessarily translate into better commercial opportunities when transport and payment arrangements are themselves constrained.
Agricultural equipment and technical services present a different model.
Irrigation technology, agricultural mechanization and post-harvest processing were specifically mentioned in the October discussions.
These activities can create recurring revenue through installation, maintenance, training and replacement parts rather than depending entirely on commodity shipments.
But a successful project must address actual operating conditions.
An irrigation system needs to fit local crop economics and water availability. Processing equipment must be supported by reliable electricity, spare parts and technical services. Storage solutions must offer measurable reductions in losses relative to their cost.
The strongest opportunities may therefore be those where Iranian suppliers combine equipment with local technical support and can demonstrate an economic benefit to a Kenyan farm, processor or distributor.
Such projects may be smaller than the infrastructure investments discussed at diplomatic meetings, but they can also be easier to test commercially.
The Kenyan Side: Tea Is Both an Opportunity and a Warning
Trade between Iran and Kenya is not limited to Iranian exports.
For Kenya, tea is central to the relationship.
In 2024, Kenya reported approximately $45.2 million in exports to Iran under the combined coffee, tea and spices category, accounting for most of its recorded bilateral exports.
Iran has historically been a significant market for Kenyan black tea, making the relationship important to producers, traders and exporters.
Yet this established market has faced a serious commercial dispute.
Kenyan authorities reported restrictions affecting tea exports to Iran following allegations that lower-grade tea had been blended and sold as higher-quality Kenyan produce.
During the seventh Kenya–Iran Joint Commission meeting in August 2025, the two countries agreed to establish a joint mechanism to address the problem and restore confidence in the trade.
The proposed solution involved stronger quality controls and documentation.
By late September 2026, the dispute had still not been fully resolved publicly. Iranian officials were reported to be seeking additional documentation before normal trade could resume.
The case illustrates a problem that can easily be overlooked in bilateral trade discussions: even a market with established demand can become commercially inaccessible when trust and product verification fail.
It also shows why the reported value of historical exports should not be confused with unrestricted current market access.
For Kenyan suppliers hoping to expand sales to Iran, traceability, quality assurance and credible documentation will be central to rebuilding commercial relationships.
Coffee presents a smaller opportunity. Kenya has a well-established coffee export industry, and Iranian demand provides a potential market, but bilateral coffee trade remains far below the scale of tea.
For Iranian importers, expanding purchases of Kenyan agricultural products will also depend on foreign-exchange availability, import regulations, financing and domestic demand.
The near-term value of stronger cooperation may lie in restoring reliable trade channels for familiar products before trying to establish entirely new ones.
Can Kenya Really Serve as Iran’s Gateway to East Africa?
Kenya’s regional position is an important part of the investment argument.
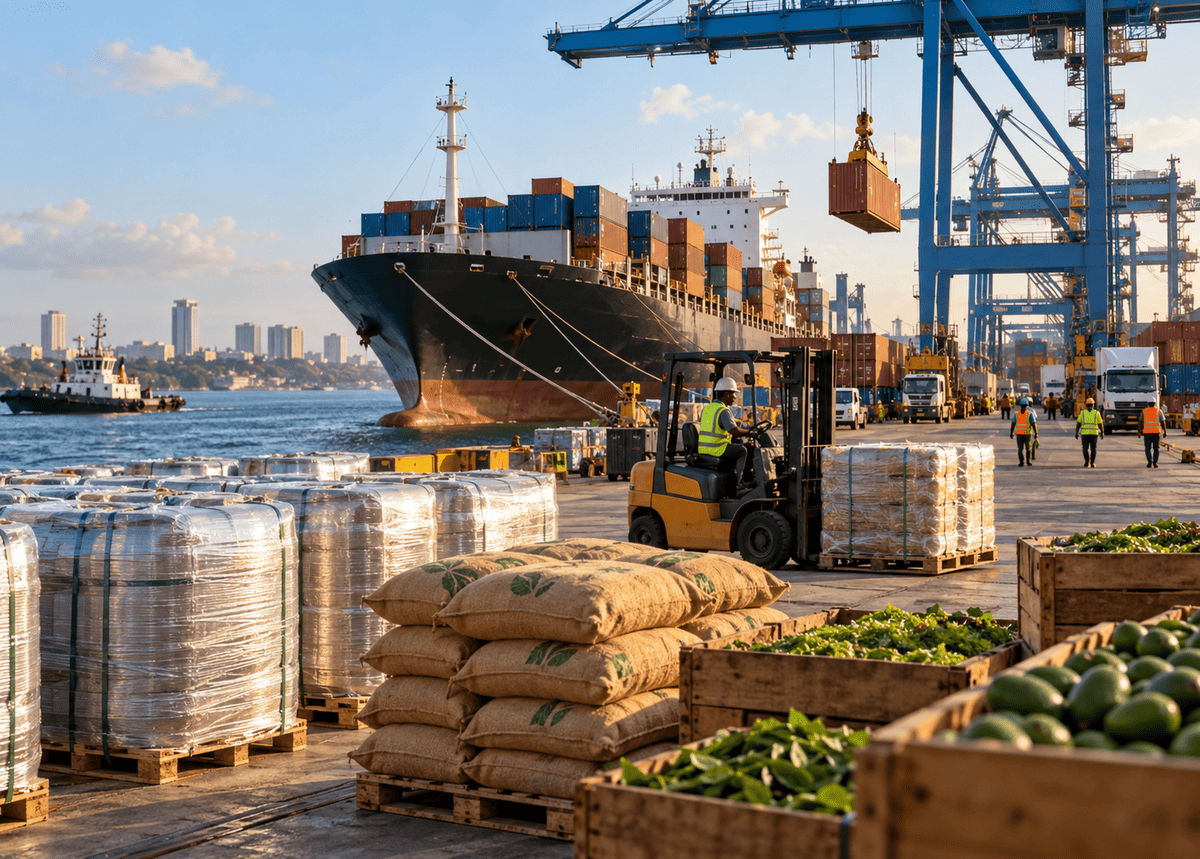
The Port of Mombasa connects maritime trade with inland transport networks serving Uganda, Rwanda, Burundi, South Sudan, eastern Democratic Republic of Congo and other markets.
The Kenya Ports Authority reports direct connections with more than 80 ports worldwide and describes Mombasa as a major gateway to East and Central Africa.
The port also connects to inland container depots in Nairobi, Naivasha and Eldoret, extending cargo-handling services towards the regional hinterland.
This infrastructure can make Kenya commercially attractive to a foreign supplier seeking access beyond Nairobi and Mombasa.
But access to a regional corridor should not be mistaken for automatic access to a regional market.
An imported product may still face customs procedures, taxes, transport costs and regulatory requirements at its ultimate destination.
Kenya is a member of the East African Community, which applies a Common External Tariff to many imports from outside the bloc. The tariff framework includes bands of 0%, 10%, 25% and 35%, while certain sensitive products may face different treatment.
The applicable rate depends on the product’s classification and current legal provisions.
Goods imported into Kenya from Iran do not automatically become Kenyan-origin products simply because they are stored, repackaged or distributed there.
For firms considering regional distribution, the distinction between importing goods into Kenya and producing goods that qualify for regional origin treatment is especially important.
A Nairobi-based distribution business may make sense when customer concentration, warehousing and inland logistics support it. Local assembly or manufacturing could change the economics in some sectors, but only after assessing the relevant origin rules, manufacturing costs and market scale.
Kenya should therefore be evaluated as a potentially useful commercial base, not as a shortcut around the individual requirements of African markets.
The Practical Barriers: Standards, Logistics and Payment
The commercial distance between Tehran and Nairobi is greater than the geographic distance suggests.
An Iranian exporter entering Kenya must address several requirements before a shipment can generate revenue.
The first is regulatory compliance.
The Kenya Bureau of Standards administers conformity requirements for imported goods, including its Pre-Export Verification of Conformity system for applicable products.
Depending on the product and the arrangements in force, documentation, testing, certification or destination inspection may be required.
These checks should be completed before shipment whenever possible. Discovering a certification problem after cargo reaches Mombasa can create storage costs, delays or additional inspection expenses.
Kenya has also introduced a relevant new documentation requirement.
Under its Finance Act 2026 guidance, importers have been required since September 1, 2026, to obtain and retain export declarations or equivalent customs documentation from the country of export.
These records must be retained for at least five years and should support the declared origin, value, quantity and classification of the imported goods.
This matters directly for companies considering transactions with Iranian suppliers. Accurate export and import documentation is not simply administrative paperwork; it can affect customs valuation, origin claims and clearance.
The second issue is logistics.
Freight costs should be assessed for the actual route, product and delivery date. Gulf shipping conditions, carrier acceptance, marine insurance and port-handling arrangements may all influence whether a transaction is viable.
For some products, direct imports may be practical. For others, small shipment sizes or specialized handling requirements could make an otherwise competitive product uneconomical.
The third issue is payment.
International restrictions affecting Iran complicate banking relationships, insurance and counterparty acceptance.
The legal position is not identical for every product or transaction. The treatment of food, medicine, industrial products and dealings involving designated entities can differ substantially.
Businesses must therefore assess the applicable sanctions, counterparties, banks and payment arrangements rather than assume that a proposed commercial exchange is permitted or executable.
A buyer’s willingness to purchase a product is not sufficient if the transaction cannot be financed, settled and delivered lawfully.
Claims that barter arrangements or bilateral agreements can solve these difficulties should also be assessed cautiously. Neither provides an automatic exemption from customs, banking or sanctions requirements.
Where Cooperation Has the Best Chance of Producing Results
The most credible opportunities differ in their level of commercial maturity.
Bitumen has an existing export market, identifiable competitors and recorded transaction volumes. The immediate task is to defend or increase market share through reliable pricing, specifications and delivery.
Pharmaceuticals and medical equipment offer potential, but product registration and market access must come before ambitious manufacturing plans.
Agricultural equipment and processing services may support smaller, practical partnerships where buyers can quantify their economic benefits.
Fertilizers have an existing, though limited, bilateral trade base. Additional sales depend on seasonal demand, product suitability and logistics.
On the Kenyan export side, restoring predictable tea trade may deliver benefits more quickly than establishing entirely new sectors. Resolving the quality and documentation dispute would also help rebuild trust between commercial partners.
Large infrastructure projects, including power generation, road construction and water systems, should be treated separately.
They require project-specific procurement, financing, technical qualification and long-term contractual arrangements. Diplomatic willingness to cooperate does not establish that a project is funded or open to foreign participation.
For an Iranian company considering entry, a useful first test would be to secure an identifiable Kenyan customer, establish the product’s regulatory and tariff treatment, obtain a realistic landed-cost calculation and confirm a compliant payment arrangement.
Only after these conditions are satisfied does it become meaningful to compare direct exporting with local distribution, technical cooperation or investment in Kenyan production.
From Commercial Interest to Measurable Trade
The October 2026 discussions demonstrate continued interest in expanding Iran–Kenya economic relations. They also follow years of cooperation initiatives, trade targets and business delegations whose results have been uneven.
The existing figures suggest that the relationship has room to expand, but not uniformly across all sectors.
Iran already holds a position in Kenya’s bitumen market. Its pharmaceutical and fertilizer exports have a smaller base from which to develop. Kenyan tea has established demand in Iran but faces unresolved trade barriers.
Kenya’s port and distribution networks could support wider East African operations, provided the economics justify them and regional trade requirements are satisfied.
The strongest next step is not another broad list of possible cooperation sectors. It is identifying transactions where demand, price, compliance, delivery and payment can all be demonstrated.
For Iran and Kenya, progress will ultimately be measured less by the number of agreements announced than by the number of commercial relationships that can operate reliably after those agreements are signed.